Search for a travel credit card in India and you’ll find the same kind of advice: top 5 cards, best premium card, best card for international travel, best card for miles, best card for hotels.
The problem? There isn’t one best travel credit card. There is only the best card for what you actually want to do.
Start with the trip, not the card
Ask yourself where you want to travel: Dubai, Singapore, London, Paris, the Maldives, Japan, Europe, the US. Then ask how you want to travel: economy, premium economy, business class, a luxury hotel, or a combination. Your answer can completely change which card makes sense.
The highest reward rate isn’t automatically the best
Say Card A gives you a higher reward rate than Card B. Easy decision? Then you discover that Card B’s rewards transfer to the airline you actually fly, while Card A’s aren’t particularly useful for your plans. Suddenly the higher rate doesn’t tell the whole story. Comparing cards purely on “X points per ₹100” can be misleading. The more useful question is what those rewards can actually do for you.
Your destination should shape your card strategy
Planning a trip to Dubai, you might care about flight availability, airline transfer partners, points required, taxes and fees, hotel options, international spending and lounge access.
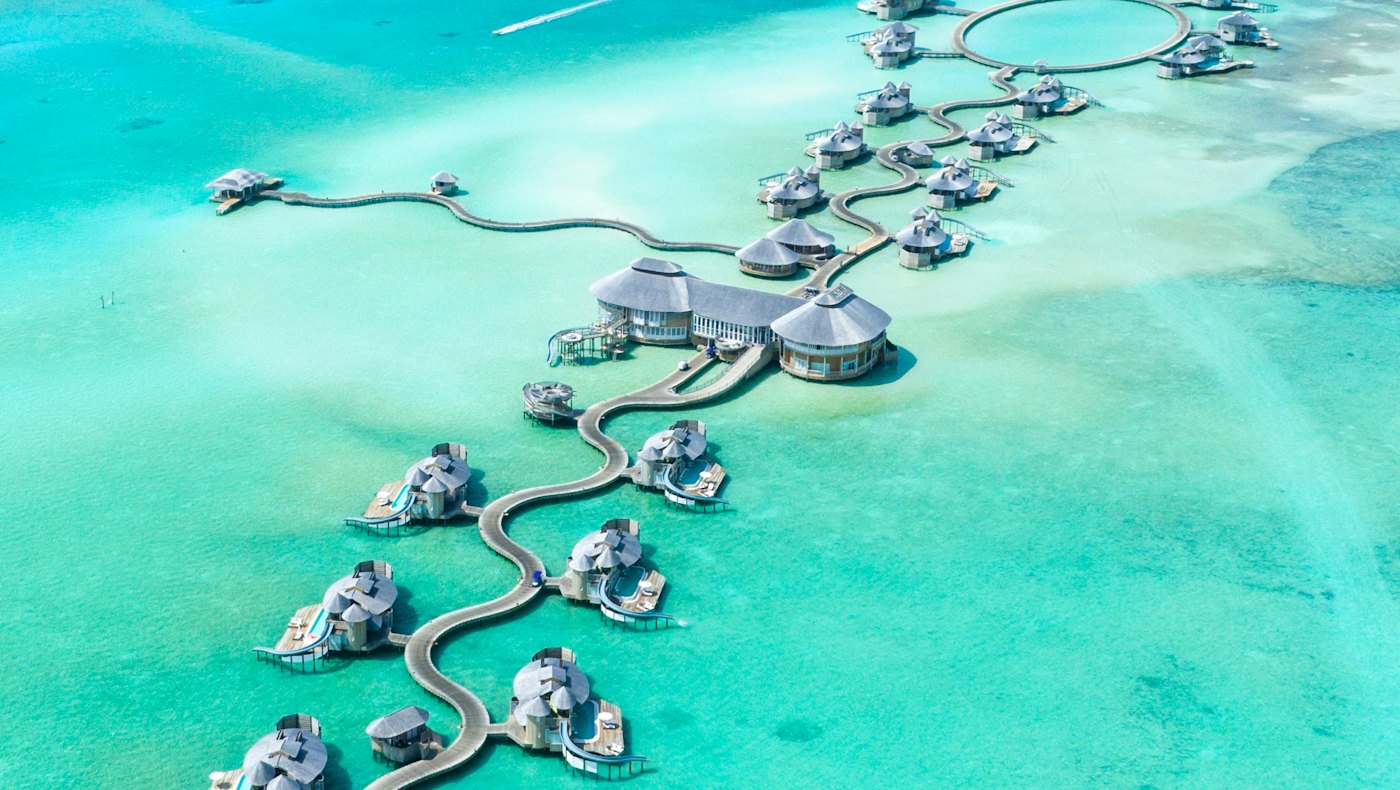
Planning a luxury stay in the Maldives, your priorities might be hotel transfer partners, hotel loyalty programmes, elite benefits, award-night availability and resort redemption value.
Same traveller. Different trip. Potentially a different rewards strategy.
Then there’s business class
A cash business-class ticket can cost far more than economy, so some travellers use miles or transferable points for premium cabins. But a good redemption isn’t simply “I have enough points.” You need to consider the airline, route, dates, number of seats, points required, taxes, transfer ratio, and whether award availability is actually there. Points and miles aren’t just about collecting. They’re about planning.
Your spending habits matter too
Your travel goals are only half the equation. The other half is how you spend.
TRAVELLER A
Spends heavily on flights, hotels, dining and international purchases.
TRAVELLER B
Spends heavily on online shopping, groceries, utilities and everyday purchases.
Giving both the same card recommendation doesn’t make much sense. A card that works beautifully for one pattern may be mediocre for the other.
Don’t start with “Which card should I get?”
Start with “What am I trying to achieve?” For example, a business-class trip to Europe:
- GoalBusiness-class trip to Europe
- Airline optionsMultiple
- Transfer partnersCompare
- Points requiredCalculate
- Current rewardsCheck
- Cash priceCompare
- Best redemptionChoose
- Card strategyDecide
The card becomes part of the strategy. It isn’t the strategy itself.
What about the cards you already have?
You might already have 40,000 points on one card, 60,000 on another, 20,000 airline miles and 30,000 hotel points. Separately, each balance may seem insignificant. Together, they could contribute to a much bigger trip. Constantly asking “What’s the best credit card?” can distract you from the more useful question: what can I do with the rewards I already have?
The problem with endless comparison
You can spend hours reading about reward rates, annual fees, welcome bonuses, transfer ratios, lounge benefits, milestones, caps, exclusions and eligibility rules. Then you find another card, and another. Before you know it, you’re comparing 15 cards when you only wanted to know: “Can I use my rewards to get to Singapore?”
Credit-card rewards should start with travel
Most comparisons run card → rewards → redemption. BTTP flips it: travel goal → available rewards → best options. Because the reason you collect rewards isn’t a bigger number in an app. It’s flights, hotels, international travel, upgrades and experiences you’d otherwise pay cash for.
Imagine simply asking: “I want to travel to Singapore. What can my existing rewards do for me?” Or “I have 75,000 points. Where can I realistically travel?” Or “Which of my cards should I use for my next trip?” Those are far more useful questions than “Which card has the highest reward rate?”
Before you apply for another card, do this
- Pick a travel goal. Where do you actually want to go?
- Look at your existing rewards. Don’t start from zero. Check everything you’ve already earned.
- Find the possible redemption paths. Airlines, hotels, travel portals, transfer partners.
- Compare the actual value. Look at cash prices versus points.
- Only then consider another card. If your current cards can’t get you there, start looking. Our credit card recommendation tool ranks cards on your spend, categories, preferred transfer partners and fee limit.
Your next card shouldn’t be chosen by a leaderboard
“Best travel credit card” lists can be useful. But they don’t know your wallet, your next destination, how much you spend, which airline you prefer or how many points you already have. You do. That’s why your rewards strategy should start with you.
Credit-card points aren’t the destination. They’re the means to one: a flight you’ve been planning, a hotel you’ve wanted to stay at, a business-class seat.
Editorial content for general information only. Card features, fees, offers and partner rules change often. Always verify current terms, eligibility and conditions with the issuer before acting.
All articles